Roofing financing options in Gilbert, AZ let homeowners fix a failing roof on the roof's timeline instead of the next paycheck's. A small leak ignored during monsoon season can turn into structural rot within weeks, so spreading the cost through a loan or payment plan often protects the rest of the home for less than the price of waiting.
Why Finance a New Roof Instead of Waiting
Arizona's intense UV exposure and sudden summer storms make delay expensive. A roof deck already weakened by sun damage tends to fail faster once monsoon rain finds the soft spot.
Financing a roof replacement lets the repair happen on the roof's schedule, not the budget's. In our experience replacing roofs across Gilbert, homeowners who finance early almost always spend less than those who wait for a small leak to become a full deck replacement.
If the damage came from a storm, it's worth checking storm damage restoration and insurance claim assistance first. Insurance may cover more of the cost than financing would need to.
Ways to Pay for a New Roof: Core Financing Options
Homeowners comparing roofing financing options in Gilbert, AZ generally choose from three lanes:
- Contractor-arranged payment plans
- Traditional loans or credit (personal loans, home equity, credit cards)
- Government-backed programs, including HUD Title I
Each lane suits a different credit profile, budget, and timeline. Most Gilbert roofing contractors can walk through all three during a single estimate visit.
Contractor Financing Plans
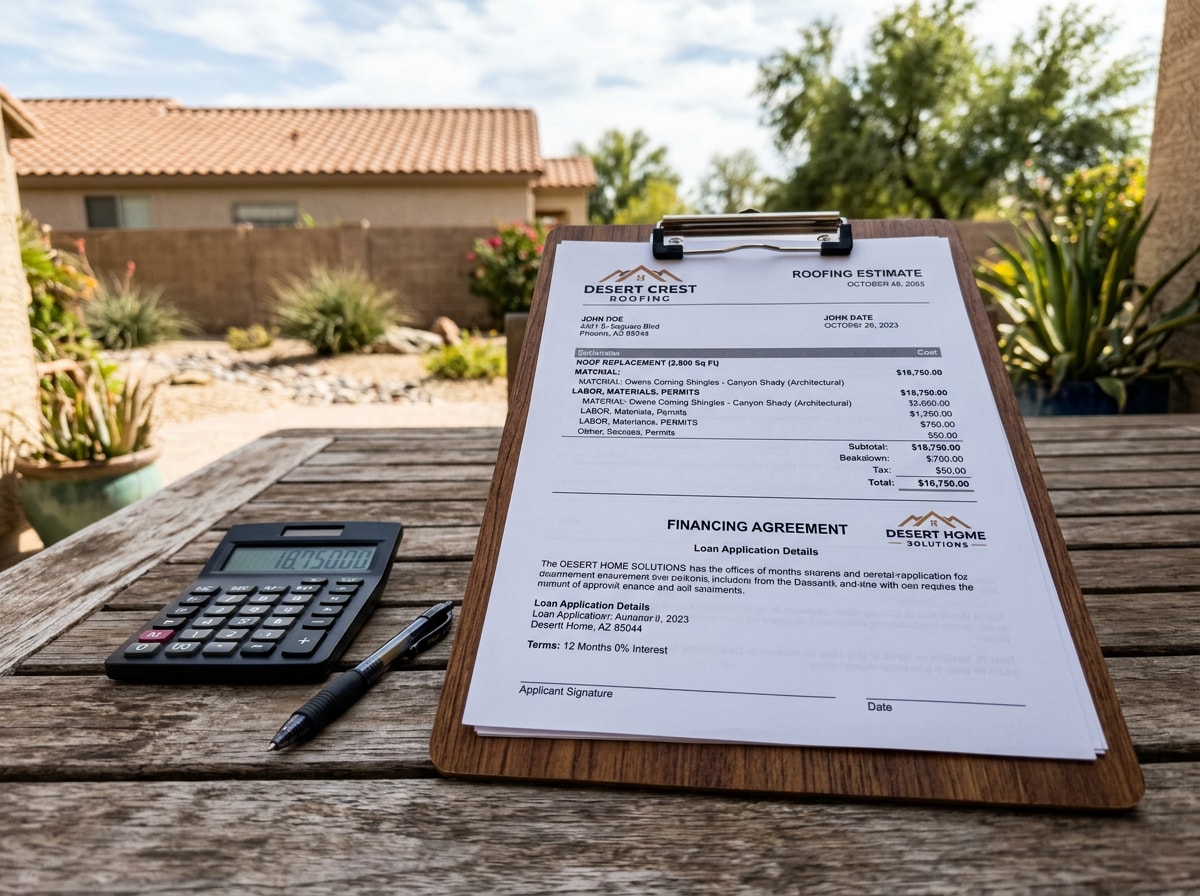
Contractor financing is usually the fastest path to a finished roof. The roofing company partners with a third-party lender, so the estimate, application, and decision often happen in one visit, sometimes with same-day approval and no down payment.
Common structures include a 0% introductory window, a fixed-APR term stretched across five to ten years, and a short no-interest plan meant to be paid off quickly. Here's roughly how those options compare on a $12,000 roofing project:
| Plan Type | Term | Rate | Est. Monthly Payment | Total Cost |
|---|---|---|---|---|
| 0% Intro Plan | 12 months | 0% if paid in full | ~$1,000 | $12,000 |
| Fixed-APR Plan | 7 years | ~9.9% APR | ~$190 | ~$15,960 |
| Short-Term No-Interest | 24 months | 0% | ~$500 | $12,000 |
These figures are illustrative. Actual rates depend on the lender and the applicant's credit profile. For a deeper look at how local companies structure these plans, this guide to roofing companies with payment plans in Phoenix breaks down common lending partners and terms.
Personal Loans, Home Equity Loans & Credit Cards
Outside contractor plans, many homeowners use a personal loan through a bank, credit union, or online lender. These unsecured loans don't put the house up as collateral, but they typically cost more in interest than secured options.
A home equity loan or HELOC often carries a lower rate because the loan is secured by the property itself, though that also means the home backs the debt. Smaller repairs sometimes go on a 0% intro credit card, but that rate disappears once the promotional period ends.
FHA Title I / HUD Home Improvement Loans
An FHA Title I loan is a government-insured property improvement loan for borrowers who may not qualify for conventional financing. HUD doesn't set a minimum credit score for the program, but it expects lenders to thoroughly review a borrower's credit history, including pulling a credit report , so the real approval bar is set by the individual lender.
The loan amounts and terms are fixed by HUD and don't vary by lender:
| Property Type | Max Loan Amount | Max Term |
|---|---|---|
| Single-family home |
Single family house - $25,000
|
Single family house - 20 years
| Manufactured home (real property) |
Manufactured house on permanent foundation - $25,090
|
Manufactured house on permanent foundation - 15 years
| Manufactured home (personal property) |
Manufactured house (classified as personal property) - $7,500
|
Manufactured house (classified as personal property) - 12 years
|
The loans are usually secured by your property, but if you borrow less than $7,500, you can obtain an unsecured loan. For current eligibility rules and lender lookup tools, see HUD's Title I Insured Programs page.
Financing Options for Homeowners with Bad or Limited Credit
Credit challenges don't have to mean living under a failing roof. Bad-credit roof financing in Arizona is usually achievable through a combination of approaches rather than one single product: FHA-backed loans, contractor payment plans, and home equity options.
Lenders reviewing a low-credit application often weigh home equity, co-signers, or program-specific guidelines more heavily than the credit score alone. Approval frequently comes down to matching the right loan type to the applicant's full financial picture.
Home Equity Options for Moderate Credit
Credit unions in Arizona sometimes approve a home equity loan for moderate credit scores when property value supports the request, since equity lending leans more on home value than credit history. That's a contrast to traditional personal loans, which typically need a higher score unless a cosigner or secured asset offsets the risk.
Mobile and Manufactured Home Roof Financing
Manufactured homes often have metal or low-slope roofs that are repaired or recoated rather than fully torn off, which keeps costs lower but can make some lenders less familiar with the work.
HUD Title I manufactured home loans cover eligible improvements, as shown in the table above. Rural Gilbert-area homeowners who meet income limits may also qualify through the Single Family Housing Repair Loans and Grants program, which provides loans to very-low-income homeowners to repair, improve, or modernize their homes, or grants to elderly very-low-income homeowners to remove health and safety hazards . Loans are termed for 20 years through this program. Details and eligibility maps are on USDA Rural Development's Single Family Housing Repair Loans and Grants page.
Commercial Roof Financing
Business owners usually finance roofing through a commercial bank loan, an equipment or property improvement loan, or SBA-backed lending. Loans backed by SBA make it easier for small businesses to access affordable funding with more flexible terms and added support, and finding the right SBA-guaranteed loan program is the first step before connecting with lenders. Review the current options on the SBA's loan programs page.
Because commercial roofs involve larger crews and longer timelines, lenders typically want the scope, roofing system, and schedule finalized before reviewing a loan application. Owners exploring roofing contractor services in Gilbert should gather these project details early.
Other Things to Consider When Financing Your Roof
Several variables shape which option fits best:
- The roof's current condition and size
- Time of year and urgency
- Total project cost
- How quickly funds are needed
Storm damage needing immediate attention may call for faster-approval financing, while a planned replacement allows time to compare rates. Some energy-efficient roofing upgrades also qualify for utility rebates, offsetting part of the project cost.
Homeowners anywhere in Gilbert, AZ can get a clearer picture of total cost by starting with a free roof inspection, which gives a firm number to finance against instead of a rough guess.
FAQ
Can I Finance a New Roof in Arizona?
Yes. Homeowners can finance a roof in Arizona through contractor payment plans with a lending partner, personal loans, home equity loans or lines of credit, and government-insured programs such as HUD Title I. Most Gilbert roofing companies outline financing options during the estimate visit.
Do You Offer Financing for Roof Replacement?
Many Gilbert roofing companies offer roof replacement financing through third-party lending partners, including 0% introductory plans for qualified applicants and fixed-term options for larger projects. Approval is typically based on credit profile, project cost, and the lender's underwriting guidelines.
What Credit Score Do I Need to Finance a Roof?
It varies by financing type. Contractor plans sometimes approve scores in the 600s, personal loans often want 640 or higher, and HUD Title I loans have no HUD-set minimum, though lenders still review credit history before approving. Approval isn't guaranteed at any score.
How Do I Pay for a Roof on a Mobile Home?
Mobile home roof payment options include personal loans, contractor financing plans, or loans insured under HUD's Title I program through an approved lender. A manufactured home roof loan may also qualify for USDA repair assistance in eligible rural areas.
How Fast Can I Get Approved for Roof Financing in Gilbert, AZ?
Contractor financing plans are usually the fastest, with some lenders offering same-day decisions during the estimate visit. Bank loans, home equity products, and HUD Title I loans generally take longer because they involve more documentation.
Ready to see real numbers for your roof? Schedule a free inspection and get a firm quote to finance against, or visit the AIM Services Roofing homepage to see the full range of services available to Gilbert homeowners.