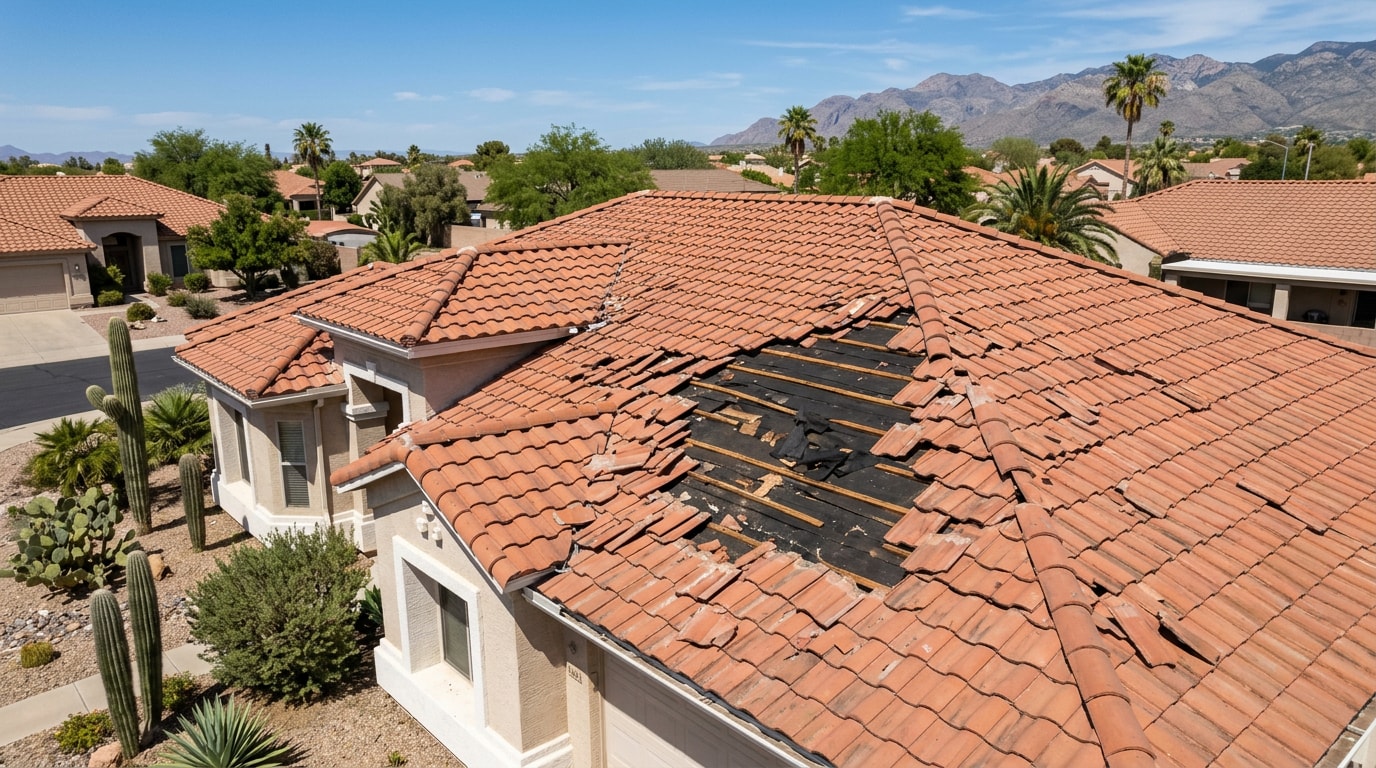
Roofing insurance claims for storm damage in Chandler, AZ follow a specific sequence, and skipping a step is usually what costs homeowners money. A microburst can strip tile or tear underlayment in minutes, but insurers only pay for damage you can prove happened that way. Below is the process, the local cost ranges, and the red flags worth knowing before anyone sets foot on your roof.
This guide is maintained by the team at AIM Services Roofing, a licensed Arizona roofing contractor serving Chandler and the East Valley. After monsoon season, our crews typically walk dozens of local roofs in the same week, and the damage we find most often shows up in spots adjusters don't check from the ground: tile valleys, areas behind ridge caps, and flashing under solar mounts. Questions about a specific roof? Contact us.
Does Homeowners Insurance Cover Storm Damage in Chandler, AZ?
Most Arizona homeowners policies cover sudden, storm-related roof damage, including monsoon wind, microbursts, hail, and wind-blown debris. They generally exclude damage from age, neglect, or gradual wear. That distinction matters because adjusters look closely at cause before approving a claim.
A standard HO-3 policy typically insures against direct physical loss unless a specific exclusion applies, rather than requiring every peril to be labeled "sudden and accidental." The Insurance Information Institute breaks down which disasters are covered and which are excluded under a typical homeowners policy.
One detail specific to Arizona: standard policies here don't carry a hurricane deductible, since that type of deductible only applies in states with coastal hurricane exposure. Your regular wind/hail deductible applies instead. If you're unsure whether your situation qualifies, our insurance claim assistance team can walk your roof and tell you honestly if it's claim-worthy.
Storm-Chaser Red Flags and Scam Warning Signs
After nearly every monsoon, out-of-state crews sweep through Chandler neighborhoods offering a "free roof" in exchange for an on-the-spot signature. It's a recognizable pattern, and it's worth knowing before anyone climbs your roof.
Watch for these tactics:
- Unsolicited door-knocking right after a storm, before you've even called your insurer
- Pressure to sign an assignment-of-benefits form immediately
- Vague promises that insurance will "cover everything"
- No local address, just a magnetic sign on a truck
- No willingness to provide a license number on request
No License, No Local Address
If a contractor can't produce a current license number or a real local address, walk away. Both checks take less than five minutes and are free.
You can verify any contractor through the Arizona Registrar of Contractors search tool, which shows license status, classification, and complaint history. Pair that with a search for a physical local address. A legitimate Chandler roofer has an office or service location, not just a truck.
How to File a Roof Insurance Claim in Chandler, Step by Step
Filing doesn't have to feel overwhelming if you follow the sequence in order. As a general timeline: within 24 hours you'd photograph visible damage, within a few days a roofer inspects the slopes, and within two to three weeks an adjuster typically visits before any supplement gets approved. Carriers vary, so treat this as a rough expectation rather than a guarantee.
1. Document the Damage Safely First
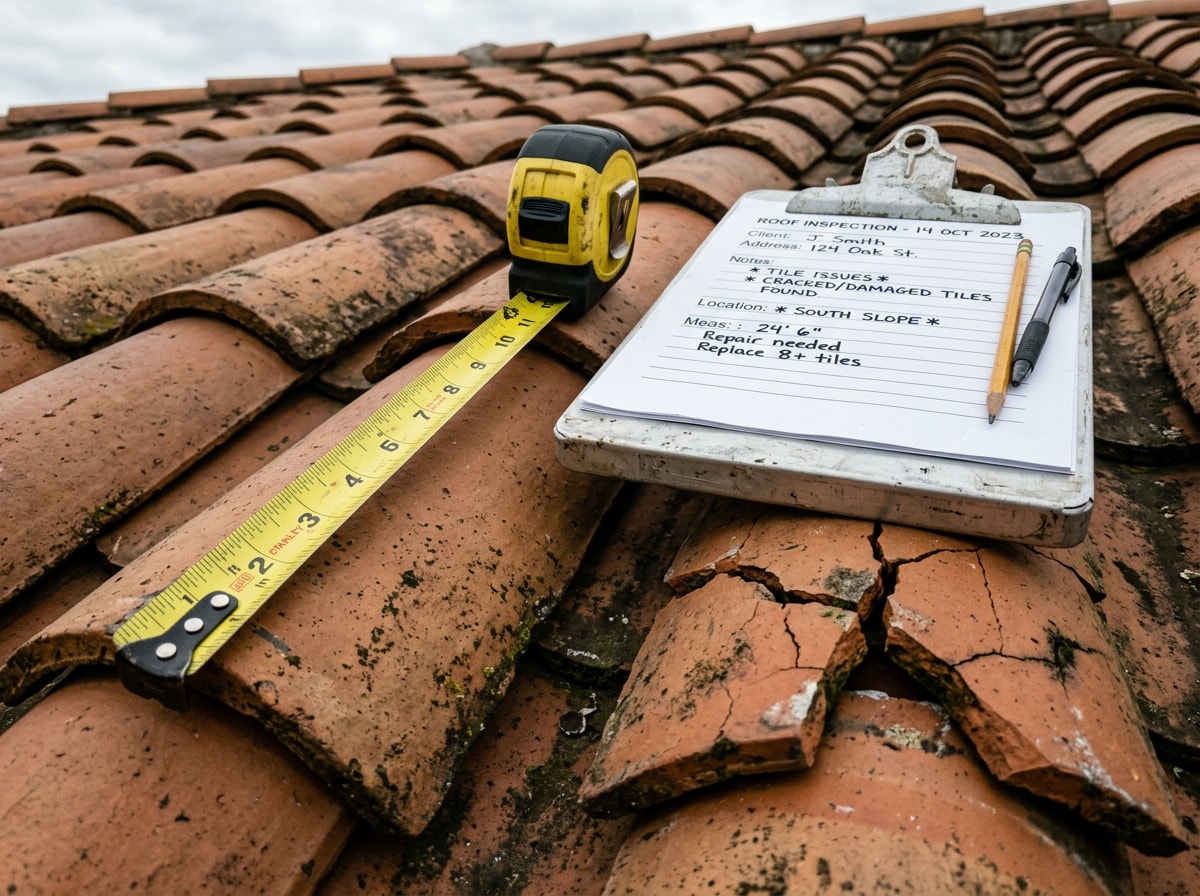
Photograph visible damage from the ground right after the storm, including missing tile, scattered debris, and ceiling stains, using a dated, time-stamped phone camera. Never climb onto a wet or storm-damaged roof yourself.
Once it's safe, a roofer should walk each slope and build a formal, adjuster-ready photo and measurement record. That documentation becomes the backbone of everything that follows, including the repair scope your adjuster will eventually reference.
2. Schedule a Professional Roof Inspection Before Calling Your Insurer
A professional inspection before you file gives you an independent, dated baseline of damage before anyone from the insurance side sees your roof. It's harder to dispute documented findings than a verbal description after the fact.
A thorough roof inspection should note slope-by-slope condition, material type, and any pre-existing wear so nothing gets unfairly blamed on the storm. You can schedule a free inspection before you contact your carrier.
3. File Promptly, Then Meet the Adjuster
Contact your insurer as soon as reasonably possible and keep a written log of every call, date, and claim number. Arizona insurers are required to acknowledge a new claim within 10 working days under the state's unfair claims settlement practices rule, and must generally complete their investigation within 30 days unless circumstances make that unreasonable, according to the Arizona Administrative Code. Filing promptly, instead of waiting, keeps that clock working in your favor.
Having your roofer present during the adjuster's visit helps make sure nothing gets missed. Adjusters cover a lot of ground daily and don't always catch every damaged section on a tile roof.
4. Handle Supplements if the Scope Falls Short
If the initial scope misses items like code-required upgrades, matching discontinued tile, or flashing replacement, your roofer can request a supplement. Many policies include an endorsement for code-upgrade coverage when local building code requires better materials or methods than what was originally installed. Our storm damage restoration team handles this supplement process directly with carriers when the first scope comes back short.
Chandler Storm Damage Patterns by Neighborhood
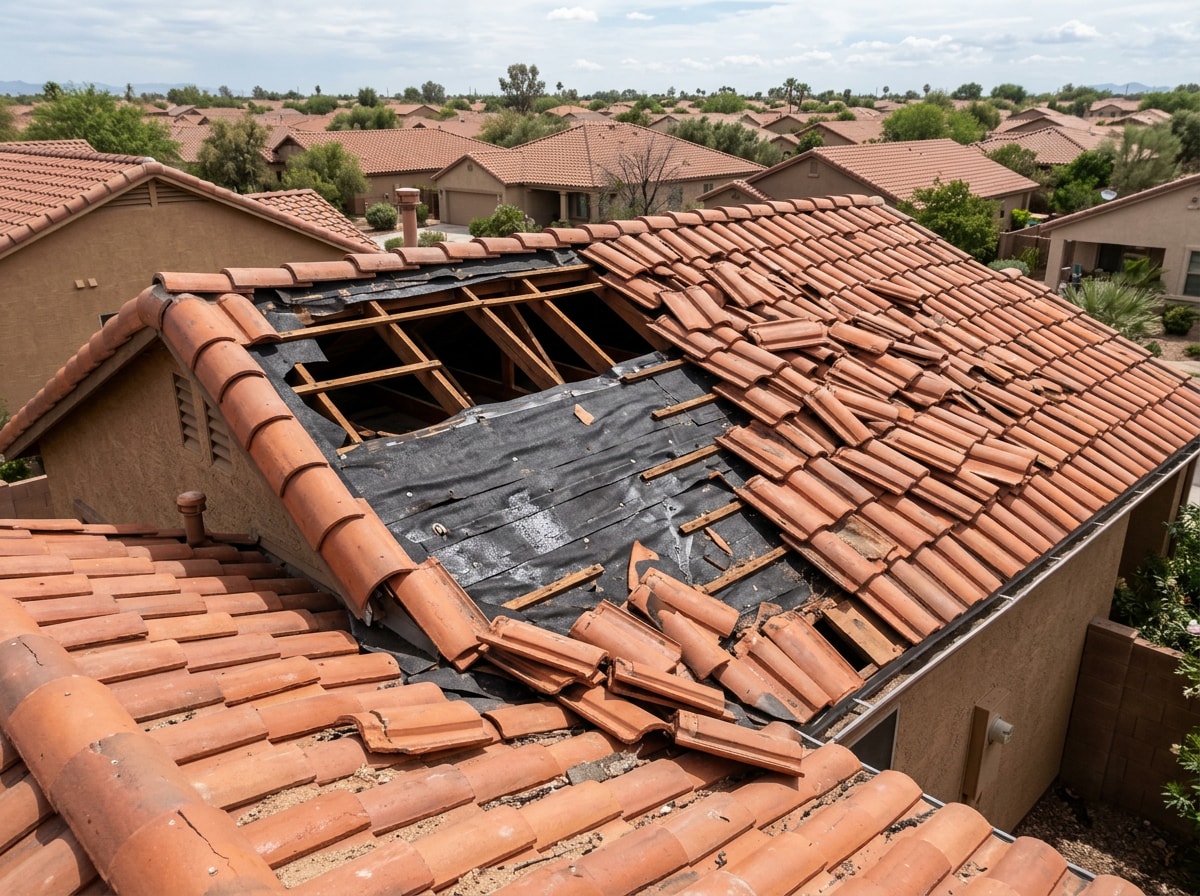
Storm damage in Chandler doesn't look the same everywhere. Ocotillo and central Chandler (85248) tend to see straight-line wind effects during microbursts, including lifted ridge caps and sectional tile loss. Fulton Ranch and the Price Corridor more often report wind-lifted tile paired with water intrusion underneath.
| Neighborhood | Common Damage Pattern | Typical Complication |
|---|---|---|
| Ocotillo / Central Chandler (85248) | Lifted ridge caps, sectional tile loss | Straight-line microburst wind |
| Fulton Ranch / Price Corridor | Wind-lifted tile with water intrusion | Underlayment damage hidden under intact tile |
| Sun Lakes (55+ community) | Tile cracking, partial field replacement | Discontinued tile styles needing color-match supplements |
Whether you're dealing with wind damage in Ocotillo, storm damage in Fulton Ranch, or a roof claim in Sun Lakes, mentioning your neighborhood's typical pattern to your adjuster can speed up the scope review. See more detail on our Chandler service area page.
Typical Cost of a Chandler Storm Damage Claim
Storm claims in Chandler commonly land between $7,000 and $20,000, depending on tile type, roof size, and neighborhood. Sun Lakes color-match supplements can push that figure higher, and solar panel removal and reinstallation often adds its own line item to the scope.
| Claim Scope | Typical Range |
|---|---|
| Partial tile/underlayment repair | $7,000 to $14,000 |
| Sun Lakes color-match supplement | $9,000 to $20,000 |
| Solar removal and reinstall add-on | $1,500 to $4,000 |
These are ranges, not quotes. Every roof, policy, and adjuster scope is different, and the only way to get an accurate number is a site-specific inspection through our roof repair or roof replacement teams.
For context on how often these storms occur, the NWS Phoenix 2025 monsoon season review tracks seasonal rainfall and severe weather events across the Phoenix metro, which helps explain why claim volume and scope size shift from one monsoon season to the next.
Homeowners outside Chandler dealing with similar wind exposure can find comparable guidance in our roofing companies near me guide for Queen Creek, which covers how to compare free estimates before committing to a contractor.
FAQ
Does Homeowners Insurance Cover Roof Damage in Arizona?
Sudden storm damage from monsoon wind, haboobs, or hail is typically covered under a standard Arizona homeowners policy. Damage from age, wear, or deferred maintenance typically isn't. Your specific policy, deductible, and ACV-versus-RCV terms ultimately decide the outcome.
How Long Do I Have to File a Roof Insurance Claim in Arizona?
There's no single statewide deadline for notifying your insurer, but policies typically require notice "promptly" or "as soon as reasonably possible." Separately, most Arizona policies set a one-year deadline from the date of loss for filing a lawsuit over a denied or disputed claim, so don't wait months to start the process.
What's the Difference Between ACV and RCV Roof Insurance Coverage?
Actual cash value (ACV) pays out the depreciated value of your roof, factoring in its age. Replacement cost value (RCV) covers the full cost to replace it, often released in two payments, one upfront and one after the work is completed.
Can a Roofer Handle a Storm-Damage Claim in Chandler?
A licensed local roofer can inspect your roof, document wind or water damage for the adjuster, and coordinate the claim from filing through supplement approval. That's different from a public adjuster, who negotiates the broader policy settlement on your behalf, usually for a percentage of the payout.
What Should I Do Immediately After a Monsoon Damages My Roof?
Photograph the damage from the ground as soon as it's safe, note the date and time, and avoid climbing onto the roof yourself. Schedule a professional inspection within a few days, then contact your insurer with the photos and inspection report together.
How Much Does a Storm Damage Roof Claim Cost in Chandler?
Most Chandler storm claims fall between $7,000 and $20,000, depending on tile type, roof size, and whether a color-match supplement or solar removal is involved. A site inspection is the only way to get an accurate figure for your home.
Ready to get your roof assessed before you call your insurer? Schedule a free inspection with AIM Services Roofing, or visit our homepage to see our full range of roofing and storm restoration services.